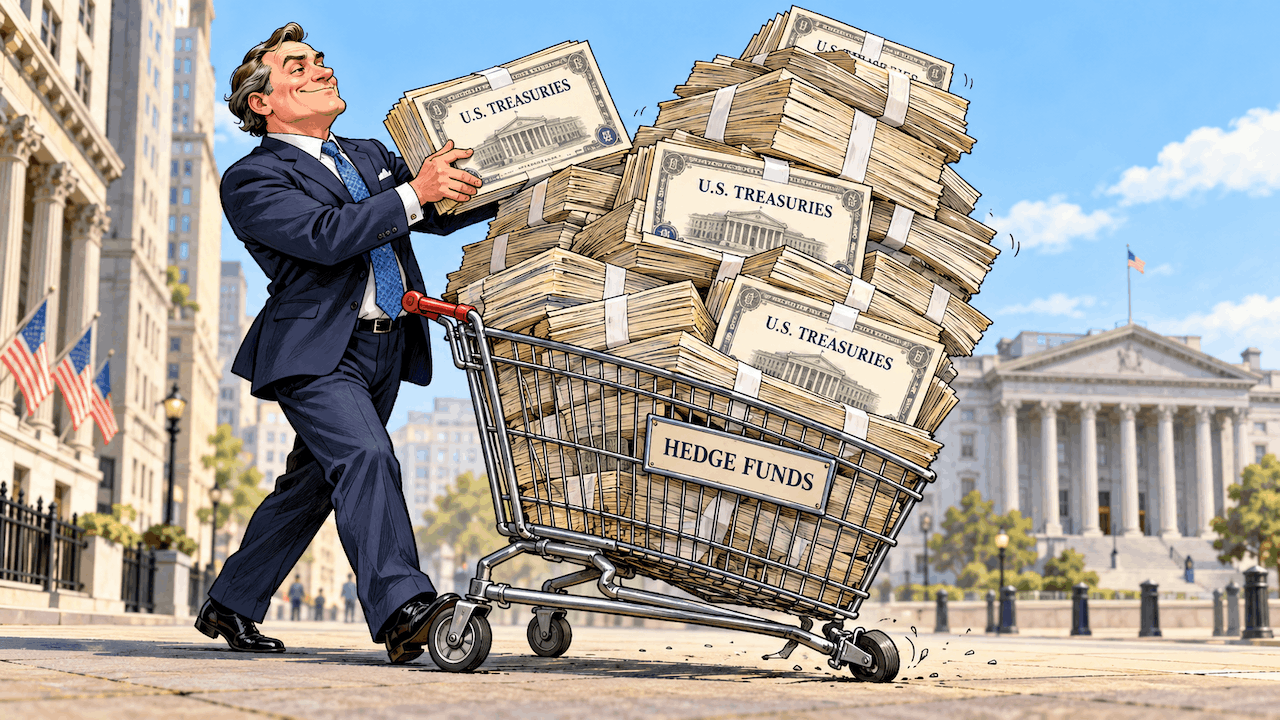
(Mike Maharrey, Money Metals News Service) The Treasury market is in meltdown, and the sector propping it up could ultimately deepen the crisis.
The 10-year Treasury yield surged to 5.33 percent overnight, the highest level since 2002. Gold Newsletter publisher Brien Lundin called it “a bond bloodbath.”
The problem is nobody wants to hold U.S. Treasuries. Foreign investors have grown wary of the United States’ deteriorating fiscal situation as it piles more debt on top of the $40 trillion it already owes. Many are also concerned about the weaponization of the dollar.
This is driving the debasement trade – an investment strategy that emphasizes holding tangible assets such as gold, silver, and other commodities to protect against the decline of fiat currencies caused by monetary debasement. We see this most clearly in central bank gold buying.
Pension funds also seem to be losing interest in bonds due to structural changes in retirement planning, including, as CNBC reported, a shift from defined-benefit plans that promise a predetermined payout to defined-contribution plans whose value depends on investment returns.
Meanwhile, the Federal Reserve is barely running enough quantitative easing to maintain its balance sheet at the current level. That means it’s only buying enough Treasuries to replace those that mature and roll off the balance sheet.
The Treasury Department has increased its bond buybacks in an effort to drive down long-term yields, but it has had no effect.
So, who is still buying Treasuries?
Hedge funds.
And that could pose a problem down the road.
Leverage Is a Risky Business
Hedge fund cash Treasury holdings reached $2 trillion at the end of 2025. That was nearly three times higher than just five years earlier. Marketable Treasury debt held by hedge funds, which is traded in the secondary market, stood at $28.9 trillion, a record 7 percent market share.
Even as other investors have shed Treasuries, hedge funds kept buying. According to Federal Reserve data, U.S. hedge funds purchased a net $60.6 billion in Treasuries in Q2, up from $26.4 billion in the first quarter.
So, that’s good news, right? Especially for a U.S. government that desperately needs somebody to keep loaning it money.
Not so fast.
As CNBC reported, “The shift is helping the government find buyers as its pile of debt grows, but it may also be making the world’s largest bond market more vulnerable, experts told CNBC.”
So, what’s the problem?
Hedge funds use a lot of leverage. In other words, they borrow money to make investments.
Union Bancaire Privée hedge fund specialist Ricky Siao called hedge funds’ use of leverage “aggressive” and warned that it magnifies “systemic risks.”
“When forced deleveraging happens due to extreme situations or crisis scenarios, it may result in broader liquidity and financial stability events.”
The Federal Reserve warned about the growing hedge fund participation in the Treasury market in its May financial stability report. It noted hedge fund leverage remained near record highs with leveraged positions “supporting significant positions in Treasurys and other markets.”
“High leverage can lead to spillovers if the fund suddenly loses access to funding.”
Earlier this year, the Bank for International Settlements (BIS) warned that the increasing role of hedge funds as “core intermediaries” in the government bond market creates “new financial stability vulnerabilities.” It said that hedge fund reliance on debt and short-term repo financing could leave “core markets” more vulnerable to “sudden deleveraging and bouts of market dysfunction.”
In other words, it could ultimately lead to a broader financial crisis, similar to the way subprime real estate drove the 2008 collapse.
Hedge funds are fond of the cash-futures basis trade. This strategy involves buying cash Treasurys while selling corresponding futures. The fund earns a small return based on the price difference between the two markets.
Agecroft Partners CEO Don Steinbrugge called this “the biggest risk,” noting that “these trades have thin margins and can often be levered 20 times, if not higher.”
“As we saw in March 2020, when Treasury market liquidity deteriorated sharply, leveraged funds can be forced to unwind positions quickly. This can create a vicious cycle of margin calls, forced selling, and further market volatility.”
Steinbrugge continued, “Hedge funds’ growing role in the Treasury market is both necessary for liquidity and a potential source of systemic risk.”
The bond market is becoming an increasingly big story. Rising yields are putting price pressure on gold and silver. However, investors may be missing part of the picture. As Treasuries tank, gold remains the last safe haven standing. People certainly won’t buy Treasuries if that particular market spirals into an even deeper crisis. It might be wise to hold precious metals to hedge against the growing potential for a broader market meltdown.
Mike Maharrey is a journalist and market analyst for Money Metals with over a decade of experience in precious metals. He holds a BS in accounting from the University of Kentucky and a BA in journalism from the University of South Florida.